
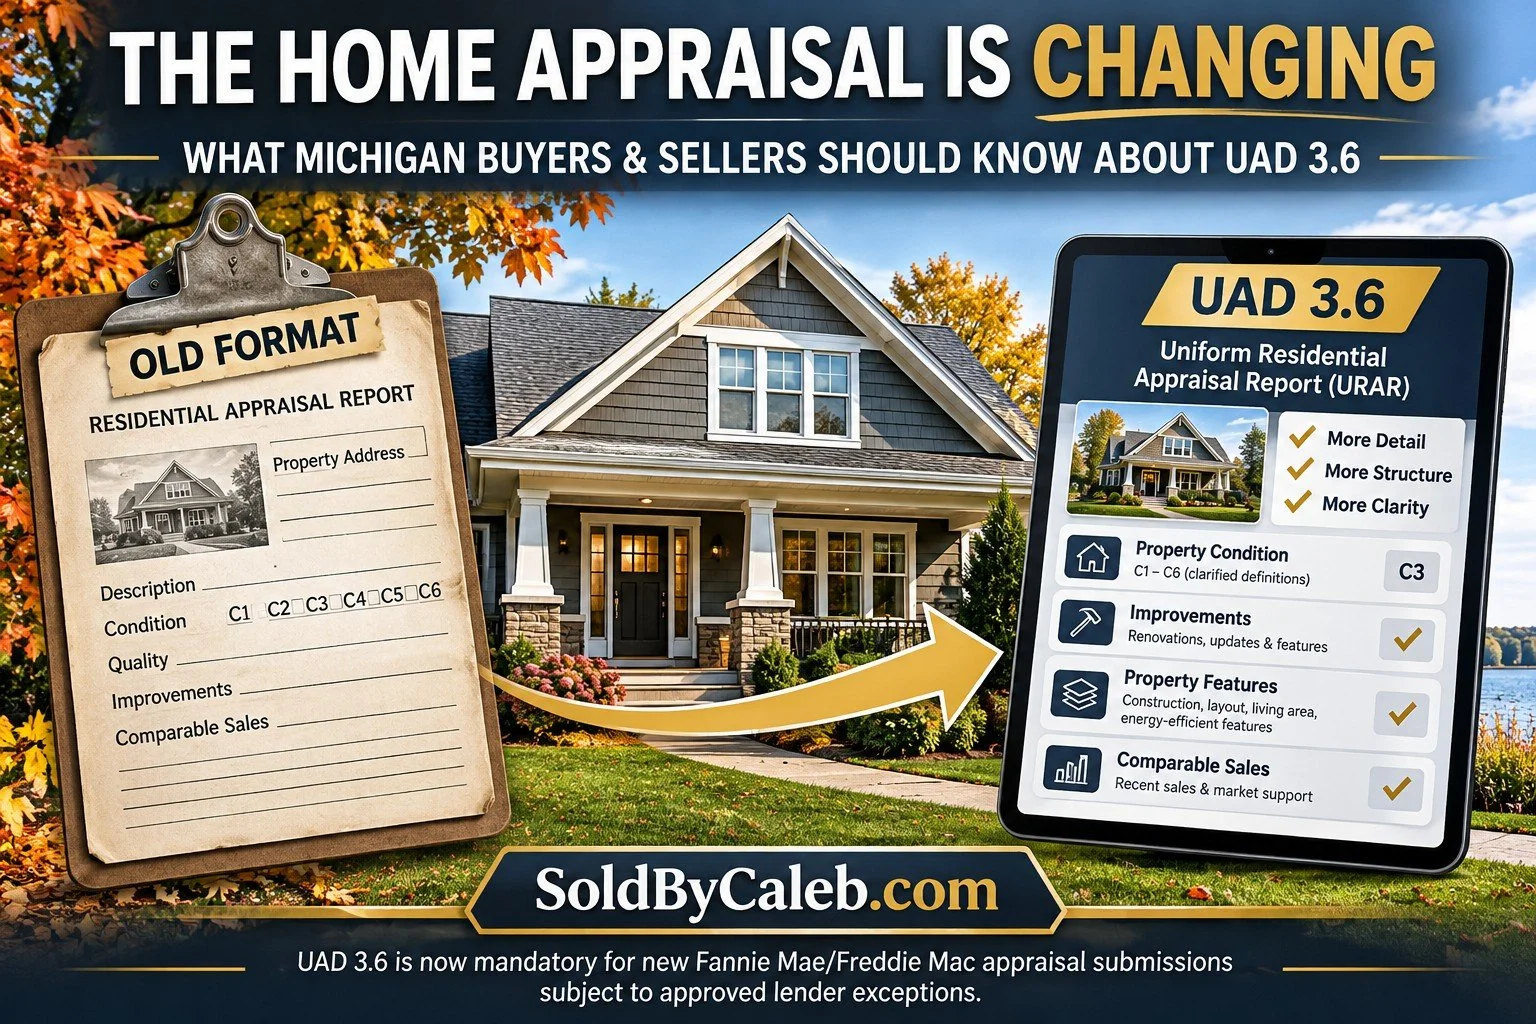
What Michigan Buyers and Sellers Should Know About UAD 3.6
Most homebuyers know that a mortgage lender may order an appraisal before approving a loan.
The appraiser studies the property, reviews comparable sales, and develops an opinion of market value.
Now, the way that information is recorded and presented is changing.
Fannie Mae and Freddie Mac have introduced a redesigned appraisal report using something called UAD 3.6. The new system provides a more detailed and organized way to describe residential properties.
Here's what Michigan buyers and sellers should know.
What Is UAD?
UAD stands for Uniform Appraisal Dataset.
It's the standard used to organize property information in appraisal reports submitted for many conventional mortgage loans.
For years, appraisers have used familiar forms with boxes, abbreviations, descriptions, photographs, and comparable sales.
The updated UAD 3.6 system replaces those older reporting formats with a flexible Uniform Residential Appraisal Report, commonly called the URAR.
The report adjusts to the type of property being appraised and provides a more structured way to document its characteristics.
When Did the Change Begin?
The transition has been underway for some time.
September 8, 2025: Limited production began for approved participants.
January 26, 2026: Broader use became available.
November 2, 2026: UAD 3.6 became mandatory for new submissions, except for lenders with approved temporary exceptions.
May 19, 2027: Last day approved lenders can submit new UAD 2.6 reports under the exception.
June 28, 2027: UAD 2.6 is retired from the submission system.
These dates concern the mortgage industry's appraisal-reporting process. Buyers and sellers generally don't need to choose a report format themselves.
For more information, visit Fannie Mae's official UAD information page.
What Is Actually Changing?
The biggest difference is how information about the home is organized.
The new appraisal report provides a more structured way to document:
Property layout, construction, and improvements
Interior and exterior condition
Construction quality
Damage, defects, and needed repairs
Energy-efficient features
Property measurements and living areas
Comparable properties used to support the value
Instead of relying as heavily on short abbreviations and general comments, the redesigned report gives appraisers more structured places to document these details.
Comparable sales remain an important part of determining market value.
For a closer look at how recent sales help establish a home's asking price, read Before Listing Your Home, Look at Comparative Sales.
A Closer Look at Condition Ratings
This is one of the more interesting changes.
Appraisers have long used condition ratings ranging from C1 through C6.
Those ratings continue under UAD 3.6, but the definitions have been clarified.
For example, a property that is relatively new may receive a different rating from a home that has been extensively remodeled. The appraiser also considers maintenance, deterioration, and repairs.
The new format allows separate condition and quality ratings for certain interior and exterior portions of a property, along with overall ratings.
Think about a Michigan home with a beautifully remodeled kitchen but an aging roof and unfinished repairs elsewhere.
The appraisal can document those different characteristics in a more organized way.
The appraiser still has to evaluate the property as a whole and support the final opinion of value.
What About Renovations and Improvements?
Homeowners often spend considerable money updating their properties.
A new roof, replacement windows, remodeled bathrooms, finished basement, or updated mechanical systems may all be relevant to an appraisal.
The updated reporting format provides more opportunities to describe a property's individual features and condition.
But the market still determines how much value buyers place on those improvements.
A $30,000 kitchen remodel, for example, does not automatically increase the home's appraised value by $30,000.
The appraiser studies how similar properties compete and sell in the local market.
Online home estimates are another way people try to understand property values. These use computer models rather than a traditional property-specific appraisal.
I've explained how these estimates work in Automated Valuation Models.
For Michigan sellers, a simple list of completed improvements can be useful when preparing for an appraisal.
Include the type of work, approximate completion date, and permits or documentation when available.
What Does This Mean for Michigan Homebuyers?
For a buyer financing a home, the appraisal remains an important part of the lender's review.
The updated report may give the buyer and lender a clearer picture of the home's reported characteristics, condition, and comparable sales.
Buyers should pay attention to:
The appraiser's opinion of value
The property's reported size and room count
Condition and quality ratings
Repairs or deficiencies noted
Comparable sales used in the analysis
Any conditions attached to the appraisal
What happens if the appraisal comes in below the purchase price?
That's where the purchase agreement becomes especially important.
The buyer and seller may be able to renegotiate the price, the buyer may contribute additional funds, or the parties may have other options depending on the contract and financing.
I've covered these situations in detail in What Happens When a Home Appraisal Comes in Low?.
Buyers should also understand how appraisal contingencies and appraisal-gap guarantees work before signing an offer.
For more information, read Purchase Agreement Basics: 11 Things Michigan Buyers Should Know.
If something appears incorrect in the appraisal, buyers can raise the concern with their lender and ask about the lender's review or reconsideration-of-value process.
An appraisal is a valuation report, not a substitute for a home inspection. The two serve different purposes.
What Does This Mean for Michigan Sellers?
Sellers can help by making accurate property information available.
Before the appraisal, consider gathering:
A list of major improvements and their dates
Building permits for applicable work
Information about finished living areas
Documentation for additions or conversions
Details about recent mechanical or structural repairs
This is particularly helpful for older Michigan homes that have changed significantly over the years.
A home built in 1965 may have new windows, updated electrical work, remodeled bathrooms, and a finished basement. Those details help explain the property's present condition.
Accurate information is more useful than trying to persuade an appraiser to reach a particular number.
Will UAD 3.6 Change Home Values?
The new system changes the reporting process, not the basic purpose of an appraisal.
Appraisers still develop an opinion of market value using accepted valuation methods and relevant market evidence.
A home's location, condition, size, features, and comparable sales continue to matter.
UAD 3.6 is intended to improve the consistency and clarity of the information used in the report.
For buyers and sellers, the practical takeaway is simple: the appraisal report is becoming more detailed, but the local real estate market still plays the central role in determining value.
Preparing for an Appraisal
Whether you're buying or selling a home in Michigan, a few basic steps remain worthwhile.
Sellers should provide accurate property details, make the home accessible for the scheduled visit, and have relevant improvement records available.
Buyers should review the completed appraisal through their lender, understand the value conclusion, and ask questions when important details appear inaccurate.
An appraisal is also just one part of the transaction. Buyers have inspections, financing requirements, title work, and other deadlines to manage.
For a practical explanation of how everything fits together, visit From Accepted Offer to Closing Day.
And both sides should remember that the appraiser's job is to develop an independent, supported opinion of value.
Final Thoughts
The appraisal industry is moving toward a more modern reporting system.
Most buyers and sellers won't need to learn the technical details of UAD 3.6. But understanding how appraisers describe a home's condition, improvements, and comparable sales can help everyone make better-informed decisions.
In Michigan real estate, accurate property information has always mattered. The new appraisal format puts even more emphasis on documenting it clearly.
SoldByCaleb.com
Real Estate. Real Guidance. Real Results.