
Homebuying Costs & Financing
Understand your budget, loan choices, down payment, closing costs, and the expenses that come with owning a home—before you commit.
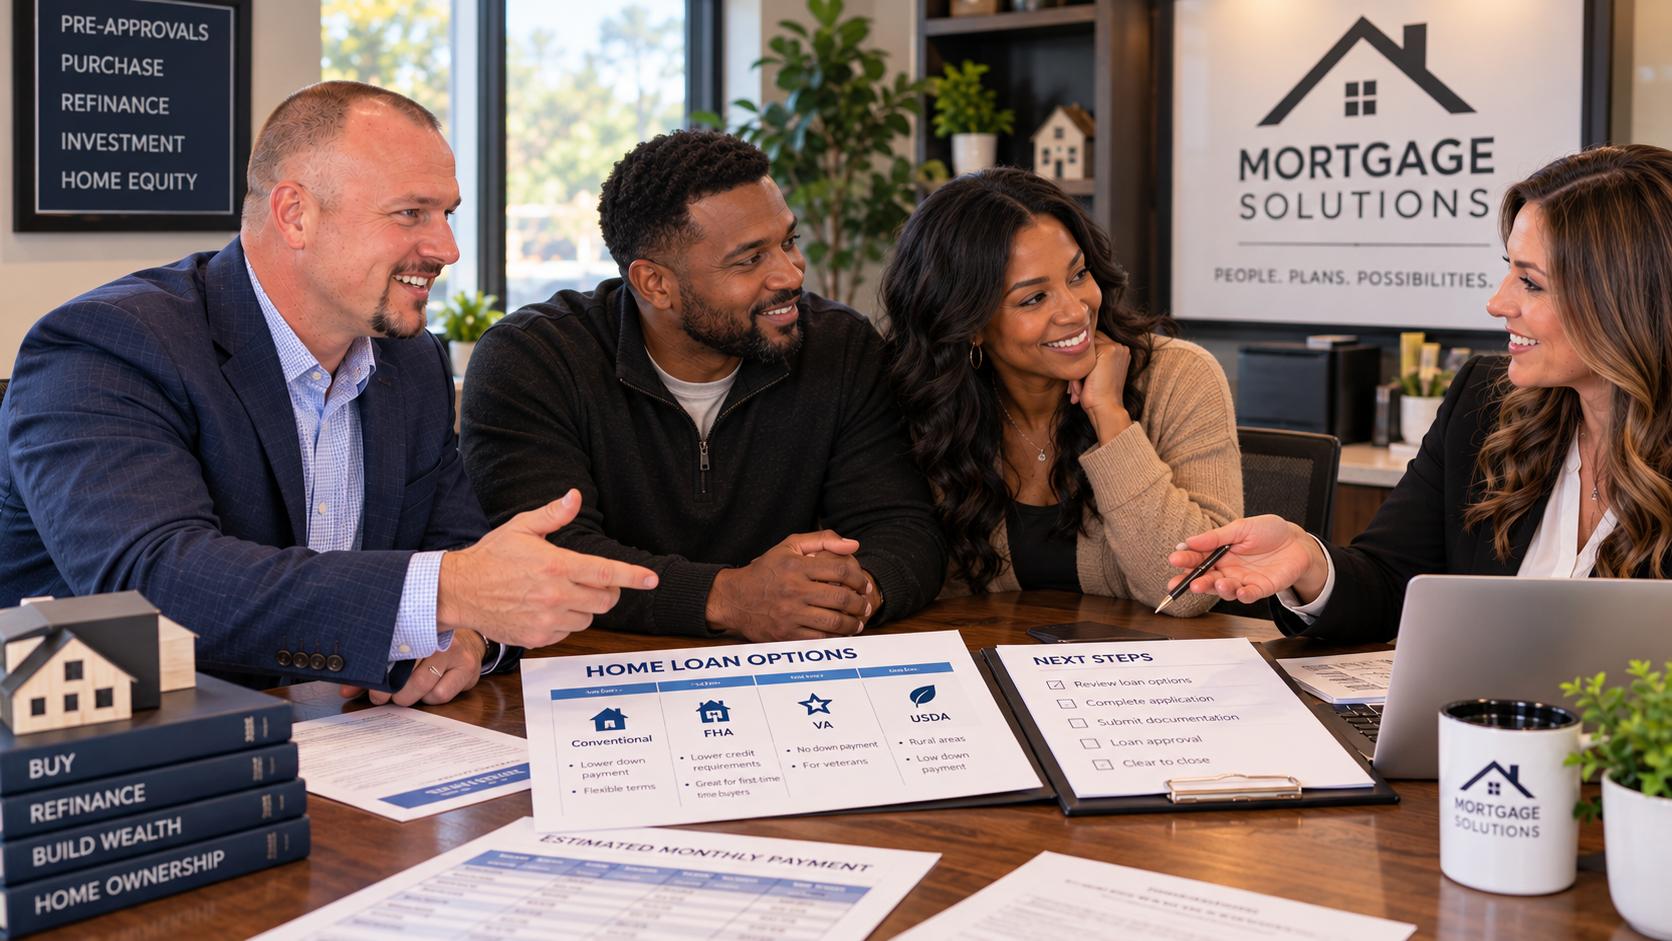
Know the numbers before you fall in love with a house
Buying a home is both a property decision and a financial commitment. Understanding the total cost early can prevent surprises and help you negotiate with confidence.
This guide explains the main costs and financing decisions for a typical home purchase. Exact loan eligibility, rates, fees, tax treatment, and contract protections depend on your circumstances. A qualified lender can provide personalized estimates.
Start with the monthly payment, not the asking price
A lender may approve a larger amount than you want to spend. Decide what payment leaves room for savings, maintenance, and everyday life.
- Ask for an estimate that includes principal, interest, property taxes, homeowners insurance, and any HOA dues.
- Account for commuting, utilities, upkeep, and anticipated repairs.
- Compare several purchase prices and down payments—not just the maximum preapproval.
Understand down payments and cash to close
A 20% down payment is not always required. Available loan programs may allow smaller down payments, depending on qualifications, property, and lender rules.
- Conventional loans may offer low-down-payment options for eligible buyers.
- FHA, VA, and USDA programs have distinct eligibility, property, and financing rules.
- A smaller down payment can affect mortgage insurance, interest rate, and the monthly payment.
- Keep money available for inspections, moving, and immediate needs after closing.
Budget beyond the down payment
The purchase price is only one part of the transaction. Costs vary by loan, location, service providers, and purchase agreement.
- Lender-related charges may include origination, appraisal, credit, and other loan fees.
- Title and settlement services, recording fees, and prepaid interest may apply.
- You may need to fund initial insurance premiums and tax or insurance escrow reserves.
- Home inspection and specialized testing costs are often paid before closing and may not be refundable.
What goes into the true monthly cost?
A mortgage payment can include several components, and some home expenses fall outside the mortgage bill.
- Principal reduces your loan balance; interest is the borrowing cost.
- Property taxes and homeowners insurance may be collected through escrow.
- Mortgage insurance may apply depending on the loan program and down payment.
- HOA dues, utilities, repairs, and routine maintenance should be budgeted separately.
Look at the loan, not just the rate
Loan choices should be evaluated using consistent assumptions. The lowest advertised interest rate is not automatically the lowest-cost option.
- Compare the same purchase price, down payment, loan term, and rate-lock assumptions.
- Review annual percentage rate (APR), discount points, lender credits, and closing costs.
- Ask whether the interest rate is fixed or adjustable and how it may change.
- Request Loan Estimates from lenders and compare them line by line.
Preapproval and financial readiness
Preapproval helps establish a realistic range and can strengthen an offer, but it is not a guarantee of final approval.
- Discuss income, assets, debts, credit, and documentation with a qualified lender.
- Ask how long the preapproval lasts and what conditions remain.
- Avoid taking on new debt or making large financial changes without discussing them with the lender.
- Keep records for significant deposits and be ready to respond promptly to underwriting requests.
Credits, contingencies, and financing risks
Offer terms can affect how much cash you need and what happens if the transaction hits an obstacle.
- Seller concessions may help with allowable closing costs, subject to loan-program limits and seller agreement.
- Financing and appraisal contingencies can matter if the loan is denied or the appraisal is below the contract price.
- Inspection terms determine when and how you can investigate the property.
- Review earnest-money obligations and every deadline before signing.
Review final numbers and protect your funds
Before closing, your lender and settlement provider should explain the final figures and required steps. For most covered mortgages, you must receive a Closing Disclosure at least three business days before closing.
- Compare the Closing Disclosure with earlier Loan Estimates and ask about unexpected changes.
- Confirm your exact cash-to-close amount and acceptable payment method.
- Verify any wire instructions using a trusted, independently obtained telephone number.
- Maintain your financial position until the transaction has funded and closed.
Your next practical step
Ask a lender for a realistic payment range and an itemized estimate of cash to close. Then talk with your buyer's agent about what that budget means for property condition, location, and offer strategy.
Ready to make a smart move?
I'm Caleb Bonderenka. As a real estate agent with more than a decade of experience and a licensed Michigan builder, I help buyers evaluate the property and understand the process—not just find a house.
Let's Talk About Your Home Search Caleb@SoldByCaleb.comThis guide is general educational information, not personalized lending, legal, tax, or financial advice. Loan terms, requirements, and fees vary. Consult your lender and other qualified professionals for your circumstances.