
Condo Basics: What Buyers Should Know Before Purchasing a Condominium
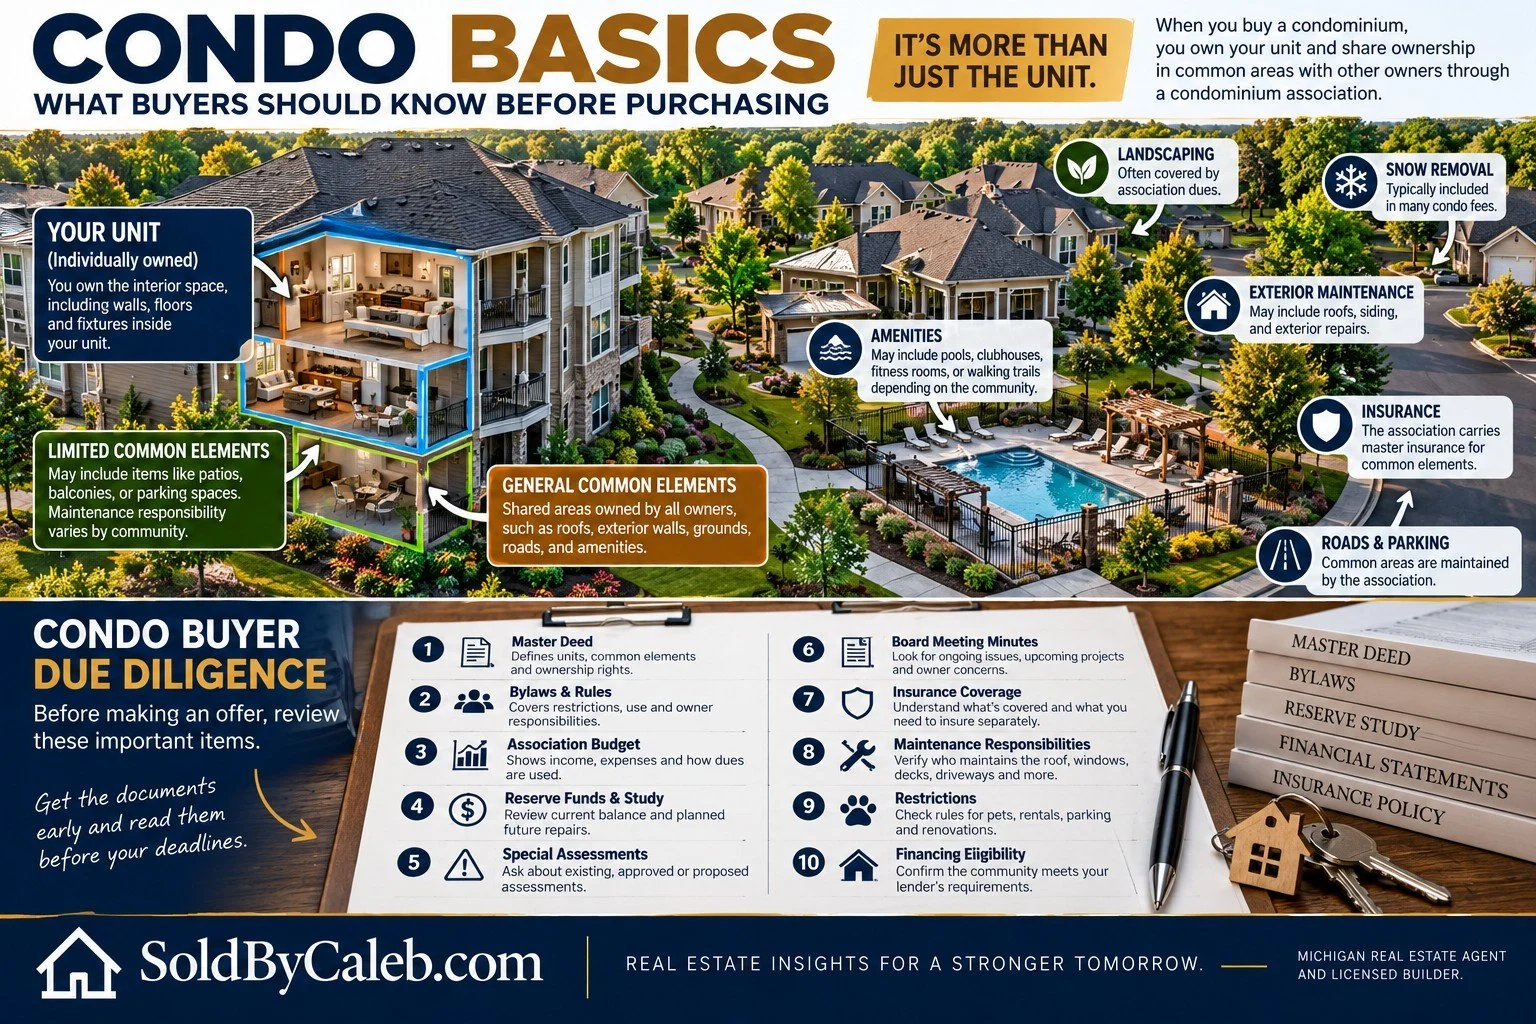
Thinking about buying a condominium in Michigan?
Condos can offer an appealing lifestyle, particularly for buyers who want less responsibility for certain exterior maintenance tasks. But condominium ownership is different from owning a traditional single family home.
Before purchasing, it's important to understand what you own, what the association controls, and what your monthly fees actually cover.
Why Do Condominiums Exist?
A condominium is a form of property ownership, not a particular architectural style.
A condo might be an apartment style unit, a townhouse, or even a detached home.
The condominium structure allows individual ownership of units while certain property and responsibilities are shared among owners.
The exact boundaries of your ownership are established by the condominium documents.
For example, a detached condominium might look exactly like a traditional single family home, but the association could be responsible for certain exterior maintenance or landscaping. In another development, the individual owner might be responsible for many of those same items.
Condo Terms Every Buyer Should Know
Master Deed: The recorded document establishing the condominium and defining units, common elements, and certain ownership rights.
Bylaws: Rules governing the association and owners, including responsibilities, restrictions, and procedures.
Association of Co-owners: The organization responsible for administering the condominium community.
General Common Elements: Shared portions of the property, potentially including grounds, roads, roofs, and other facilities, as defined in the documents.
Limited Common Elements: Areas designated for the use of certain units, potentially including patios, balconies, or parking spaces. Maintenance responsibility varies.
Reserve Fund: Money set aside for future major repairs and replacement of common elements.
Special Assessment: An additional charge imposed on owners, often to cover major expenses beyond available funds.
Reserve Study: An assessment of major common components, their expected useful lives, replacement costs, and recommended funding.
Association Dues: Regular payments collected from owners to cover the association's operating expenses and reserve contributions.
Board of Directors: The elected or appointed individuals responsible for overseeing association operations and making decisions within their authority.
What Do Condo Fees Cover?
Monthly association dues may pay for landscaping, snow removal, exterior maintenance, common area insurance, management, utilities, amenities, and reserve contributions.
But coverage varies considerably.
A $400 monthly fee that includes water, exterior maintenance, and substantial reserve contributions may be very different from a $250 fee that covers relatively little.
It's also important to understand the difference between regular expenses and additional charges.
Regular association dues: Recurring charges, usually collected monthly or quarterly, to fund the association's operations and reserves.
Special assessments: Additional charges that may be imposed to cover major repairs, unexpected expenses, or other association needs.
Transfer or administrative fees: Charges associated with a change in ownership, when applicable.
Individual insurance: Coverage for your unit, belongings, personal liability, and other risks not covered by the association's master insurance policy.
Property taxes: Generally paid separately from association dues.
Utility expenses: Some utilities may be included in association dues, while others are billed directly to individual owners.
Are Lower Condo Fees Always Better?
Not necessarily.
An association with unusually low dues might be adequately funded because it has fewer shared responsibilities.
However, low dues could also mean the association isn't collecting enough money for future repairs.
Consider a community with aging roofs, deteriorating roads, or other major components approaching the end of their useful lives.
If the reserve fund is insufficient, owners could face substantial special assessments.
The important question isn't simply how much the monthly fee costs.
It's what you're receiving, what you're responsible for, and whether the association is financially prepared for future expenses.
What Should Buyers Investigate Before Purchasing?
Before completing your due diligence, request and review the following information.
1. Master Deed and Bylaws
Understand what you own, what is considered common property, and which responsibilities belong to the association.
Pay attention to restrictions involving pets, rentals, parking, renovations, and exterior changes.
2. Association Budget and Financial Statements
Review how the association collects and spends money.
Are operating expenses covered by regular dues? Are there significant unpaid assessments or other financial concerns?
3. Reserve Funds
Find out how much money has been set aside for major repairs and replacements.
Ask whether the association has a recent reserve study and whether it is following the recommended funding plan.
4. Special Assessments
Ask about existing, approved, or proposed special assessments.
A seller may be current on regular dues while a substantial additional assessment is being considered.
5. Board Meeting Minutes
Recent meeting minutes can provide valuable insight into ongoing issues, upcoming repairs, owner concerns, and financial decisions.
6. Insurance Coverage
Determine what the association's master policy covers and what insurance you will need individually.
Pay attention to deductibles and potential responsibilities for damage involving shared components.
7. Maintenance Responsibilities
Don't assume the association handles everything outside the unit.
Verify who is responsible for:
Roof repairs and replacement
Windows and exterior doors
Decks, balconies, and patios
Driveways and sidewalks
Landscaping and snow removal
Exterior siding and painting
Plumbing and utility lines
Responsibilities can differ substantially between condominium developments.
8. Major Repairs and Building Condition
Evaluate the physical condition of shared components.
Roofs, pavement, drainage systems, foundations, retaining walls, and exterior structures can create significant expenses when repairs are needed.
This is particularly important in older condominium communities.
9. Litigation and Association Disputes
Ask whether the association is involved in pending litigation or significant disputes.
Certain legal or financial issues may affect ownership costs or mortgage financing.
10. Mortgage Financing Eligibility
Not every condominium automatically qualifies for every mortgage program.
Depending on the loan and project, lenders may review the association's finances, insurance, owner occupancy, physical condition, and other factors.
Discuss the condominium with your lender early in the process.
Condo Associations vs. HOAs
Condominium associations and homeowners associations (HOAs) can perform similar functions, but the underlying ownership arrangements may differ.
In a traditional subdivision with an HOA, owners commonly own their homes and lots while the association manages certain shared facilities and enforces community rules.
In a condominium, unit boundaries and common elements are established through the condominium ownership documents.
Both types of associations may collect dues, establish community rules, and manage shared expenses.
That's why it's important to understand the association's responsibilities and restrictions before purchasing.
Watch my video: HOA Buyer Basics on YouTube for additional information about homeowners associations and what buyers should know.
One Important Michigan Legal Detail
Michigan provides specific disclosure and withdrawal protections for certain purchases directly from condominium developers.
Under applicable provisions of the Michigan Condominium Act, qualifying developer sales may include a nine-business-day withdrawal period tied to the receipt of required condominium documents.
Those protections should not be assumed to apply automatically to every resale condominium purchase.
For resale transactions, buyers should carefully review their purchase agreement, document review deadlines, inspection provisions, and financing contingencies.
Buyers should also understand that condominium documents can be extensive. Taking the time to review them before the applicable deadlines can help prevent unpleasant surprises.
For additional information, the Michigan Condominium Buyer's Handbook is a useful resource.
Before You Make an Offer
When considering a condominium, ask about the association documents early and find out when you'll have an opportunity to review them.
Your purchase agreement should provide appropriate protections for reviewing the association's financial condition, rules, restrictions, and any potential assessments.
It's also worth speaking with your lender about condominium financing requirements before spending money on inspections and an appraisal.
The goal is to understand not only the condominium you're purchasing, but also the financial obligations and responsibilities that come with owning it.