
Michigan Property Tax Uncapping Explained: When Taxes Reset and When They Don't
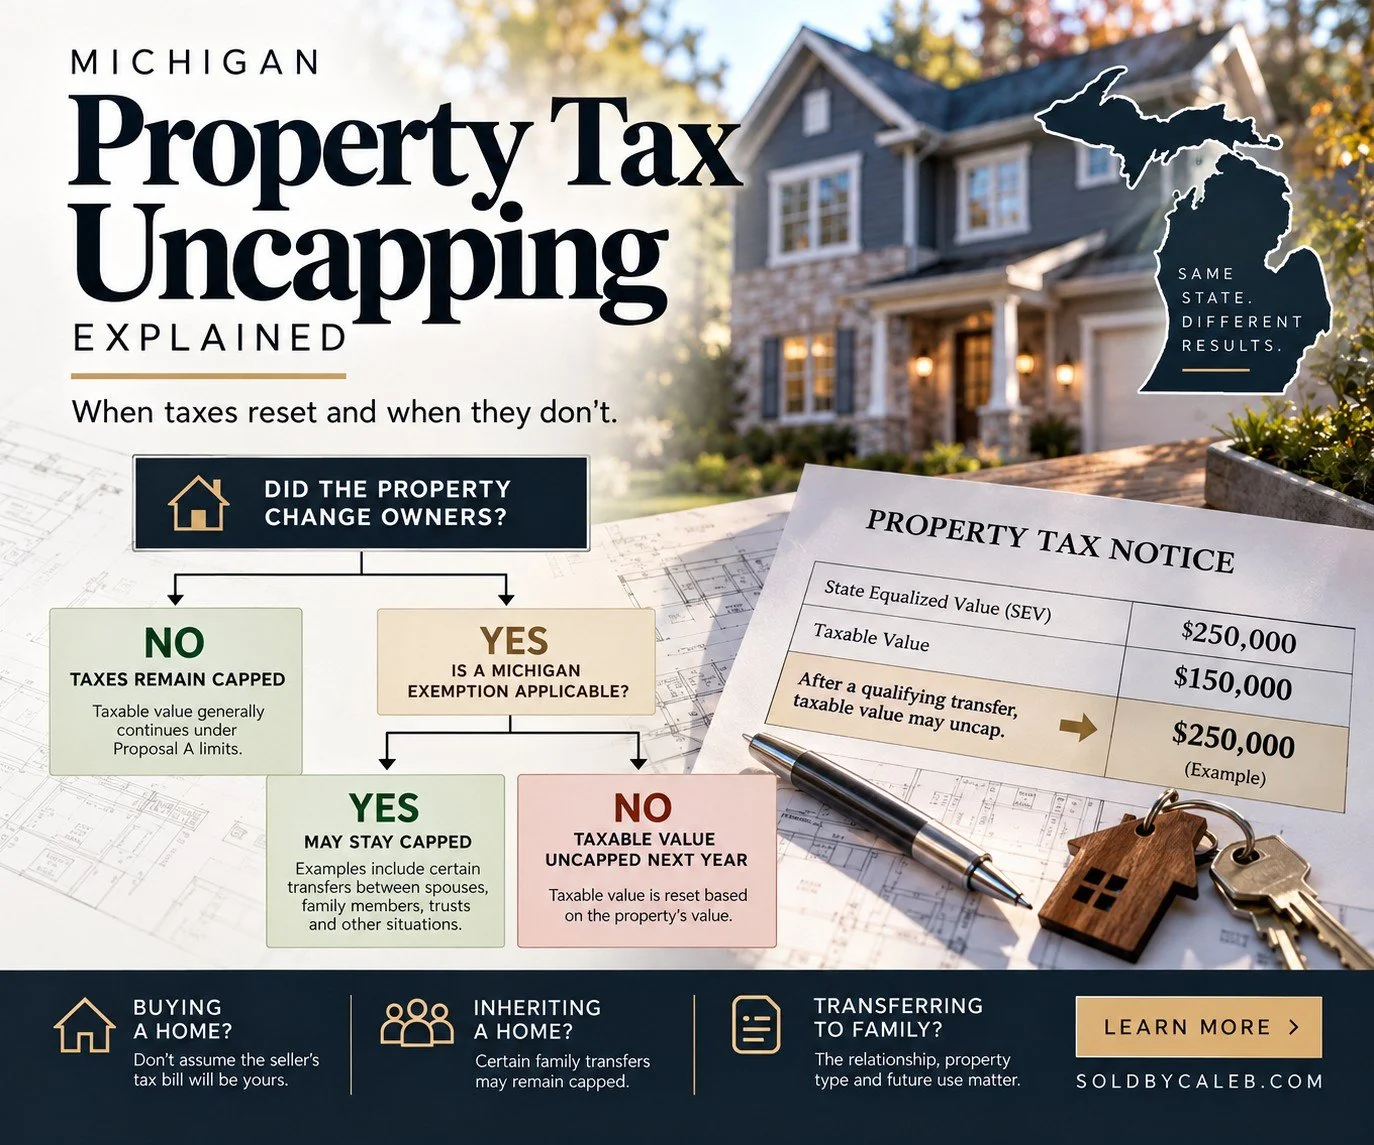
If you buy, inherit or transfer a home in Michigan, there is an important property tax rule to understand: uncapping.
Michigan property taxes do not necessarily stay the same when a property changes owners. In many cases, a transfer of ownership causes the property's taxable value to "uncap" in the following calendar year.
But not every transfer causes uncapping.
Transfers between spouses, certain family transfers, some trust arrangements and several other situations may qualify for an exemption.
Here is how it works.
First, Understand SEV and Taxable Value
A Michigan property tax bill includes two important numbers:
• State Equalized Value, or SEV: Generally 50% of the property's true cash value
• Taxable Value: The value used to calculate property taxes
Under Michigan's Proposal A system, taxable value is generally limited in how much it can increase each year while ownership remains unchanged.
Because of this, someone who has owned a home for many years can have a taxable value considerably lower than the property's SEV.
When a transfer of ownership occurs, however, that taxable value may be uncapped.
Michigan Treasury provides additional information on changes in property ownership and taxable value.
What Does Uncapping Actually Mean?
Suppose a longtime homeowner has:
• SEV: $250,000
• Taxable Value: $150,000
Their property taxes are being calculated using the $150,000 taxable value.
Now suppose the home is sold and the sale constitutes a transfer of ownership.
In the year of the sale:
The property's existing taxable value generally remains in place.
In the following calendar year:
The taxable value is uncapped and determined based on the property's value under Michigan's assessment rules.
That means a buyer should never assume the seller's current property tax bill will become the buyer's property tax bill.
The house didn't change.
The taxable value did.
If This Happens, What Happens to the Taxes?
Here are some common scenarios.
You Buy a Home From an Unrelated Seller
→ Generally considered a transfer of ownership
→ Taxable value generally uncaps the following calendar year
You Sell Your Home to Another Buyer
→ Generally considered a transfer of ownership
→ The buyer's taxable value generally uncaps the following year
You Transfer Property to Your Spouse
→ Certain transfers between spouses are exempt from transfer of ownership
→ Generally no uncapping when the statutory requirements are met
Property Passes to a Surviving Spouse
→ Certain transfers resulting from the death of a spouse are exempt
→ Generally no uncapping
You Add or Remove Your Spouse From the Property
→ An exemption may apply
→ Generally no uncapping when the transfer meets Michigan's requirements
You Transfer a Home to a Family Member
→ Certain transfers of residential real property between specified relatives can qualify for an exemption
→ The taxable value may remain capped
However, being related does not automatically prevent uncapping.
The relationship, property type and future use of the property matter.
Which Family Transfers May Qualify?
Michigan law provides an exemption for certain transfers of residential real property between specified family members when the statutory requirements are satisfied.
Depending on the circumstances, qualifying relationships can include transfers involving:
• Parents
• Children
• Adopted children
• Siblings
• Grandparents
• Grandchildren
• Certain spouses of qualifying relatives
There is another important requirement.
The property cannot be used for a commercial purpose following the transfer if the family transfer exemption being claimed requires continued qualifying residential use.
Because the exact relationship and use matter, do not assume that every transfer between relatives qualifies.
Michigan's State Tax Commission Transfer of Ownership Guidelines provide detailed guidance on these exemptions.
What If You Inherit a Michigan Home?
An inherited property does not automatically mean the taxable value must uncap.
For example:
Parent dies and qualifying residential property passes to a child
→ A family transfer exemption may apply
→ The property may remain capped if all requirements are satisfied
But change the facts and you can change the answer.
If an heir changes the property's use, transfers it again, places ownership into another entity or otherwise fails to satisfy an exemption, the tax treatment can be different.
This is why inherited property should be reviewed before deciding whether to keep it, rent it, transfer it or sell it.
What About a Trust?
Putting a home into a trust does not automatically mean the taxable value will uncap.
Certain trust transfers are specifically exempt under Michigan law.
For example, some transfers where the settlor or the settlor's spouse remains the qualifying beneficiary can avoid being treated as a transfer of ownership.
But trusts can be structured many different ways.
Do not assume that transferring a property into or out of a trust will automatically preserve the existing taxable value.
Review the trust and transfer before recording the deed.
What About Adding Someone as a Joint Owner?
This is another situation where the details matter.
Certain creation or termination of a joint tenancy can qualify for an exemption, particularly when Michigan's requirements concerning an original owner are satisfied.
Other ownership changes may constitute a transfer.
The important point is:
Adding someone's name to a deed does not automatically tell you whether the property's taxable value will uncap.
What About Transferring a Home Into an LLC?
This deserves extra caution.
A homeowner should not assume that transferring a personally owned property into an LLC will preserve the existing taxable value simply because the homeowner also owns the LLC.
Michigan has specific rules involving transfers between legal entities and commonly controlled entities.
If you are considering transferring real estate into an LLC for liability, estate planning or investment purposes, determine the property tax consequences before recording the transfer.
Other Transfers That May Be Exempt From Uncapping
Michigan law recognizes a number of situations that may not constitute a transfer of ownership when the applicable requirements are met.
These can include certain:
• Transfers between spouses
• Changes adding or removing a spouse
• Family transfers of qualifying residential property
• Trust transfers
• Joint tenancy changes
• Life estates and life leases
• Court ordered transfers
• Transfers creating or releasing a security interest
• Agricultural property transfers
• Qualified forest property transfers
• Transfers between certain commonly controlled business entities
This is not a complete list, and each exemption has specific requirements.
The Property Transfer Affidavit
Another important piece of the process is Michigan's Property Transfer Affidavit, Form 2766.
A Property Transfer Affidavit may still be required even when the transfer qualifies for an exemption from uncapping.
The form is generally filed with the assessor for the city or township where the property is located within 45 days of the transfer.
The form also provides a way to identify certain exemptions that may apply.
You can view the current Michigan Property Transfer Affidavit, Form 2766.
Failing to properly report a transfer can create problems later. If an assessor discovers an unreported transfer, Michigan provides procedures for delayed uncapping and correction of taxable values.
Buying a Home? Don't Use the Seller's Tax Bill
This is probably the most important takeaway for Michigan home buyers.
When looking at a property, don't simply see the seller's annual taxes and assume:
"That's what my taxes will be."
Instead, look at:
• Current SEV
• Current taxable value
• Estimated market value
• Whether the transaction will cause uncapping
• Current local millage rates
• Principal Residence Exemption status
• Potential taxable value after the transfer
That gives you a much better picture of the potential cost of owning the home.
Property taxes are only one part of evaluating a property. I also recommend looking carefully at the home's condition, location and potential future expenses. My guide to 9 Things Buyers Should Look for When Buying a Home covers several of those considerations.
Transferring Property to Family? Check Before You Sign
If you're considering transferring a Michigan property to a child, parent, sibling, grandchild, spouse, trust, LLC or another person, investigate the tax consequences before recording the deed.
A good checklist is:
• Identify exactly who currently owns the property
• Identify who will own it after the transfer
• Determine whether Michigan considers it a transfer of ownership
• Determine whether a statutory exemption applies
• Verify any requirements concerning the property's future use
• Complete the required Property Transfer Affidavit
• Keep documentation supporting the exemption
• Consult a Michigan real estate attorney or qualified tax professional when the situation is not straightforward
The Bottom Line
Michigan property tax uncapping sounds complicated, but the basic concept is fairly simple:
If ownership changes, the taxable value may uncap.
If the transfer qualifies for a Michigan exemption, the taxable value may remain capped.
The important part is determining which rule applies before transferring the property.
For buyers, understanding uncapping can prevent a surprise when the tax bill changes after purchasing a home.
For existing homeowners, understanding the exemptions can be especially important when transferring property within a family or as part of an estate plan.
If you're buying or selling a home in Southeast Michigan and want help understanding the real estate side of property taxes, comparable sales and the overall cost of the property, visit SoldByCaleb.com.
This article is intended for general real estate education and is not legal or tax advice. Michigan property tax exemptions depend on the facts of each transfer. Consult the local assessor, a Michigan real estate attorney or a qualified tax professional regarding a specific transfer.
Sources and More Information
Michigan Department of Treasury, Property Tax and Change of Ownership
Michigan State Tax Commission, Transfer of Ownership Guidelines