
7 Title Problems That Can Delay a Michigan Home Closing, and How They're Resolved
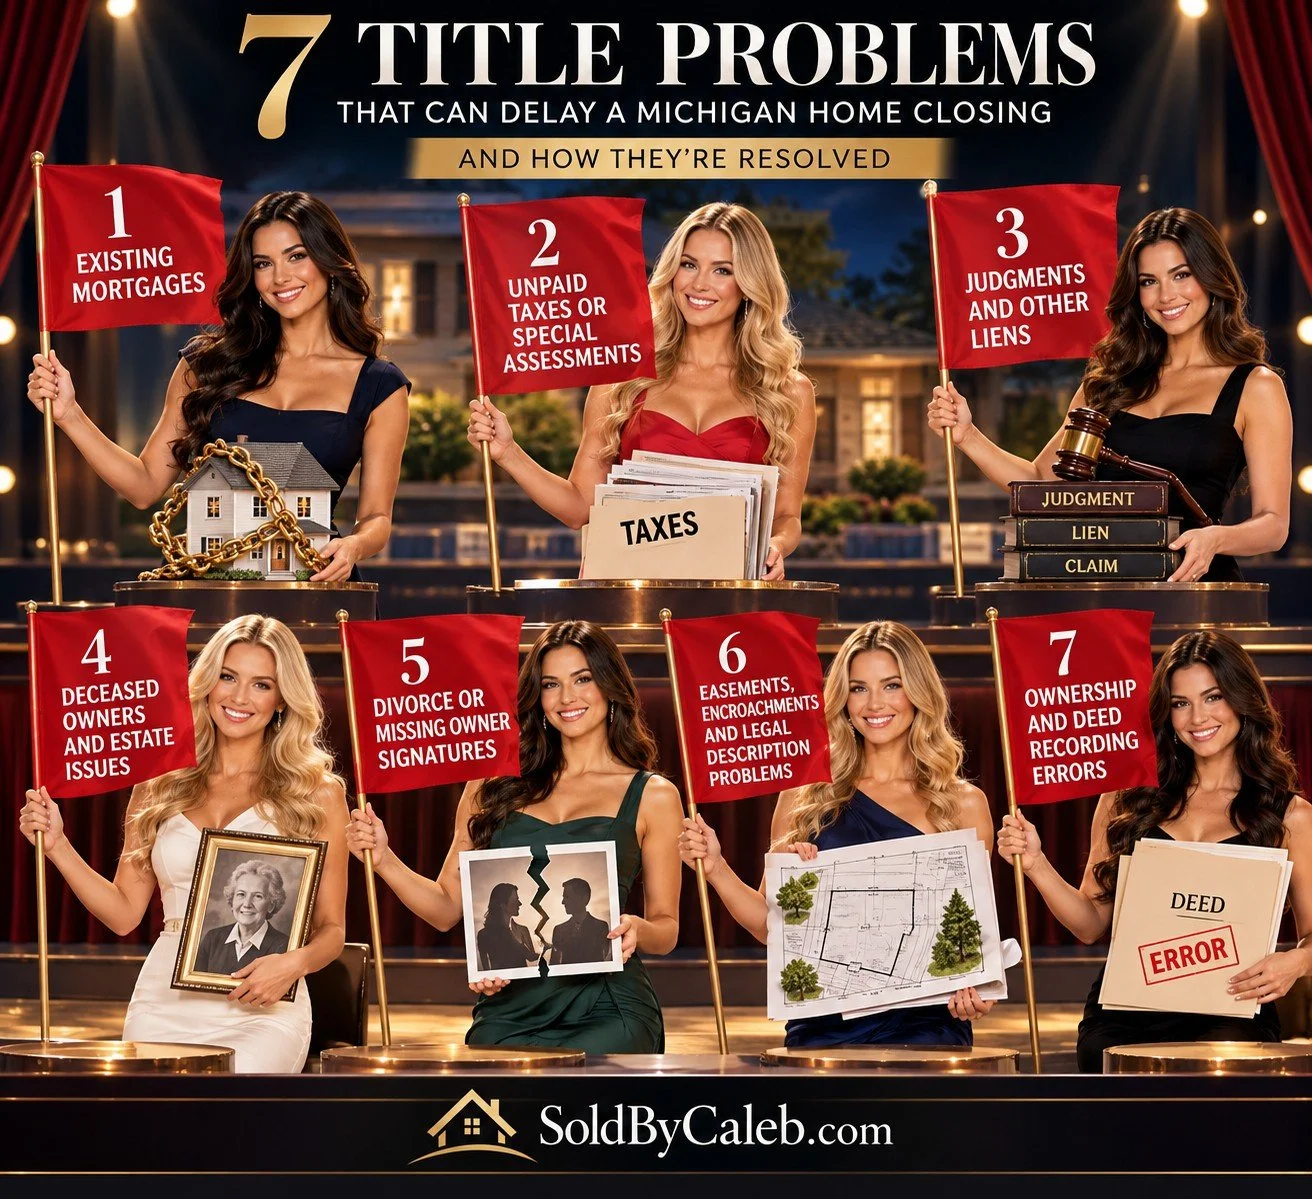
A title problem doesn't necessarily mean a home sale is in trouble. Many issues can be resolved before closing with the proper documents, payments or legal approvals.
When buying or selling a home in Michigan, the title company examines public records to identify potential problems involving ownership, mortgages, liens and other interests in the property.
The goal is to identify and resolve title issues before ownership transfers.
Here are seven problems buyers and sellers should understand, along with the steps that may help resolve them.
1. Existing Mortgages That Haven't Been Discharged
A previous mortgage may still appear in county records, even if the seller believes it was paid off.
Possible resolutions:
If the mortgage is still owed: Obtain a payoff statement and arrange for payment through closing.
If the mortgage was already paid: Request a recorded discharge or appropriate release documentation from the lender.
If the lender no longer exists or cannot be located: Additional research or legal action may be necessary.
Learn more: Michigan law on mortgage discharges, MCL 565.42.
2. Unpaid Property Taxes or Special Assessments
Delinquent taxes and certain unpaid assessments can create claims against a property and may prevent a transaction from closing as planned.
Possible resolutions:
If property taxes are delinquent: Obtain the current amount due from the appropriate treasurer and arrange for payment.
If a special assessment has an outstanding balance: Determine whether it must be paid at closing or can remain payable in installments.
If the buyer and seller disagree about responsibility: Review the purchase agreement and negotiate an appropriate allocation.
If tax foreclosure proceedings have begun: Seek immediate guidance from the county treasurer and a qualified attorney.
Learn more: Michigan Department of Treasury, Property Tax Forfeiture and Foreclosure.
3. Judgments, Construction Liens and Other Claims
A contractor, creditor or another party may have a legally enforceable claim affecting the property.
Possible resolutions:
If the lien is valid and money is owed: Obtain a payoff and arrange for payment and an appropriate release.
If the debt has already been paid: Obtain the required satisfaction, discharge or lien waiver.
If the claim belongs to someone with a similar name: Provide documentation so the title company can verify whether it applies to the seller.
If the lien is disputed: Legal assistance may be needed before the title company will insure the transaction.
Not every judgment automatically attaches to real estate, and different liens have different legal requirements.
Learn more: Michigan Construction Lien Act, MCL 570.1115.
4. Deceased Owners and Estate Issues
When a property owner dies, the right to sell the property depends on how the property was owned and whether probate or other legal procedures are necessary.
Possible resolutions:
If the property was owned jointly with survivorship rights: Appropriate death and ownership documentation may establish the surviving owner's authority.
If the property is part of a probate estate: A court-appointed personal representative may need to provide letters of authority.
If the estate representative has limited authority: Court approval or additional documentation may be required.
If heirs disagree or ownership is disputed: The matter may need to be resolved before closing.
Learn more: State Bar of Michigan, Personal Representatives and Probate.
5. Divorce or Missing Owner Signatures
A person listed on the deed may still have an ownership interest, even if they no longer live at the property.
Possible resolutions:
If both former spouses remain on the deed: Both may need to sign the necessary documents to transfer ownership.
If a divorce judgment awarded the property to one spouse: The title company may require a deed or other documentation establishing the transfer.
If an owner cannot be located: Additional legal steps may be necessary.
If ownership is disputed: The parties may need a court order or other legal resolution.
Important: Divorce does not automatically update the recorded deed.
Learn more: Quitclaim Deeds and Divorce | Michigan Legal Help
6. Easements, Encroachments and Legal Description Problems
A recorded easement may allow another party to use part of the property. An encroachment occurs when a structure or improvement extends onto another property or into an area where it may not belong.
Possible resolutions:
If an easement is recorded: Review its location and terms. It may be a permanent property right that remains after closing.
If a fence, garage or driveway crosses a property line: A survey and agreement with the affected owner may help determine a solution.
If the legal description contains an error: A corrected document or qualifying correction affidavit may resolve it.
If the property lacks adequate legal access: An access agreement, easement or legal proceeding may be necessary.
Not every easement or encroachment prevents closing. Buyers should understand which conditions will remain and whether they are excluded from title insurance coverage.
Learn more: Michigan law on correcting recorded document errors, MCL 565.451d.
7. Ownership and Deed Recording Errors
An error in a previous deed or transfer can create questions about the property's ownership history, sometimes called the chain of title.
Possible resolutions:
If a name is misspelled or a clerical mistake occurred: A correction affidavit or corrected document may be appropriate.
If a previous deed was never recorded: The original document may need to be located, evaluated and recorded.
If a required signature is missing: The appropriate party may need to execute a new or corrective document.
If competing ownership claims exist: An attorney may need to resolve the dispute, potentially through a court proceeding.
Learn more: Michigan law on correction affidavits and recorded documents.
What Happens If a Title Problem Cannot Be Resolved Before Closing?
A title issue does not automatically terminate a purchase agreement. The next step depends on the problem, the contract and the title insurer's requirements.
If the issue can be resolved with money: Payment may be arranged through closing.
If additional documents are needed: Closing may be postponed while they are obtained.
If the issue can remain without preventing the transaction: The buyer and lender may be able to proceed, subject to the title insurer's approval and applicable contract terms.
If the seller cannot deliver the title required by the agreement: The parties may need to negotiate an extension, another resolution or potentially terminate the transaction according to the contract.
A title insurer may also agree to insure over certain risks. That does not necessarily eliminate the underlying issue.
What Should Buyers and Sellers Do?
For sellers:
Disclose known ownership, lien or estate complications to the appropriate professionals early.
Locate mortgage payoff information and any existing discharge documents.
Resolve outstanding title questions before the closing deadline whenever possible.
For buyers:
Review the title commitment, including its requirements and exceptions.
Ask questions about recorded easements, restrictions and unresolved claims.
Understand the difference between lender's and owner's title insurance. A lender's policy protects the lender, not the buyer's equity.
Consider obtaining legal advice when ownership, access or boundary rights are uncertain.
The Consumer Financial Protection Bureau explains the distinction between lender's and owner's title insurance.
This article provides general educational information about Michigan real estate transactions, not legal advice. Specific title requirements, coverage and remedies depend on the circumstances, purchase agreement and applicable law.